
A late fee is a charge added to an invoice when a client pays after the due date. Most businesses deal with this regularly: nearly 3 in 5 small businesses (59%) had invoices overdue by 30 or more days last year, up from 47% the year before, according to QuickBooks’ 2026 Small Business Late Payments Report. A clear late fee policy is one of the most effective tools for protecting your cash flow and cutting down on past-due accounts.
This guide covers how much to charge, how to calculate a late fee correctly, how your rate holds up against your state’s limits, and how to roll out a policy your team and your clients can actually stick to.
Key takeaways:
- Most late fee policies charge 1% to 2% of the invoice per month, with 1.5% the most common rate.
- A late fee policy only works if it is enforced every time, without exceptions.
- State law sets real limits on what you can charge, so confirm your rate with a collections attorney before you put it in writing.
- A late fee is a flat or percentage charge for a missed due date; interest is calculated differently and may be subject to separate state limits.
- Clients need to agree to your late fee terms in a signed contract before the fee is enforceable.
- When late fees and follow-up stop moving an account, a professional collections partner can take over before the balance ages further.
Should Your Business Have a Late Fee Policy?
For most businesses, yes. A late fee sends a clear signal: your payment terms are commitments, not suggestions. The goal is not to earn extra revenue off late payers. It is to give clients a real reason to pay on time.
A late fee only works if you enforce it every time. If your contract lists a fee but you waive it the moment a client pushes back, your team just taught every client that the policy is optional. Decide on the rate, put it in writing, and apply it consistently.
How Much Should You Charge for Late Fees?
Across most industries, a monthly rate between 1% and 2% is standard, and 1.5% per month is the most common choice. Some businesses use a flat fee instead, typically $25 to $50 per missed payment.
Before you lock in a rate, talk to a collections attorney or legal advisor. Late fee limits vary by state, and some states treat a late fee as a form of interest, which means it can fall under that state’s usury law. A rate that is standard in one state can be unenforceable, or even illegal, in another. That is exactly what the next section walks through.
How to Find Your State’s Late Fee Limit
There is no single national cap on late fees. Each state regulates them through some combination of usury law, general contract law, and, in some cases, industry-specific statutes. Broadly, states fall into a few patterns:
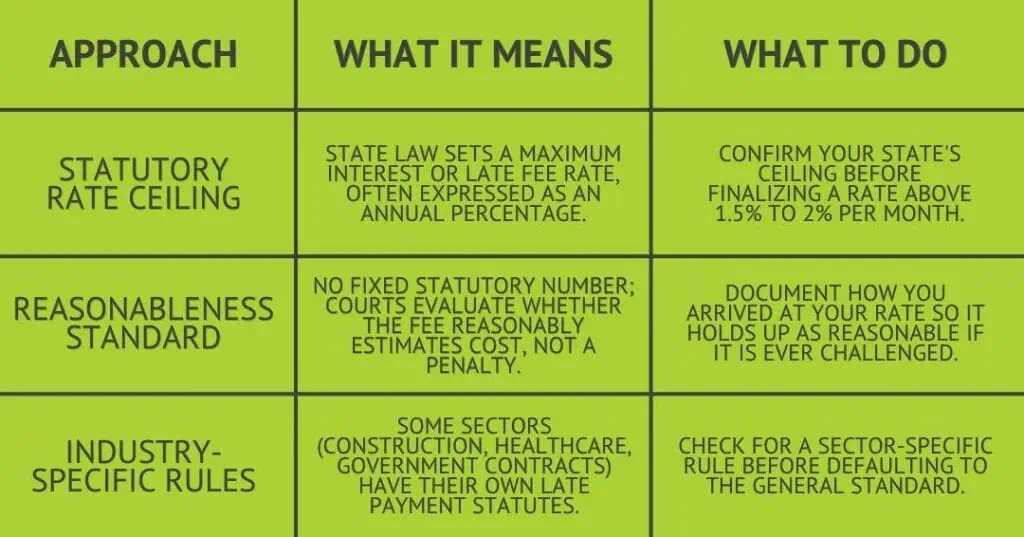
Because these rules vary by state and change over time, this guide will not assign a specific number to each one, and this is not legal advice. The National Consumer Law Center’s guide to interest rate and usury laws is a solid starting point for researching your state’s specific statute. A collections attorney should confirm the final number before it goes into a contract.
How to Calculate a Late Fee
Calculating a percentage-based late fee is straightforward. Multiply the outstanding balance by your monthly rate.
Example: A $3,000 invoice at 1.5% per month generates a $45 late fee for each 30-day period it goes unpaid.
If an invoice runs two months overdue, apply the fee to the original balance again rather than the growing total, unless your contract specifically allows for compounding.
How to Implement a Late Fee Policy
Rolling out a late fee policy works best when done step by step, not all at once.
- Consult a legal advisor first. Confirm your rate complies with your state’s law (see above) and that fees can transfer to collections if the account ages further.
- Update your contracts. Spell out the rate, the grace period, and when the fee starts. Clients need to agree to these terms before work begins.
- Put the terms on every invoice. A single line works: “A late fee of 1.5% will be applied to balances unpaid after the due date.”
- Notify current clients before the policy takes effect. Give them time to adjust and ask questions.
- Align your internal team. Everyone who touches billing needs to know the policy and apply it the same way every time. Uneven enforcement undermines the whole system.
How to Communicate Late Fees to Clients
Honesty is what keeps a late fee policy from damaging client relationships. When clients understand the terms upfront and see them applied fairly and consistently, there is far less friction when a fee actually shows up on an invoice.
Most late payments are not intentional. Clients get busy, an invoice gets misrouted to the wrong inbox, or the bill lands with someone who is not authorized to approve it. A short, friendly reminder before the due date, followed by a clear note right after it passes, resolves a large share of late payments before any fee is ever applied.
When you do need to apply a fee, say so plainly and point back to the signed contract. A line like “Per the payment terms in your agreement, a late fee of 1.5% has been applied to this balance” is direct without being confrontational. Clients respond better to a policy that is explained than one that just appears on their statement.
FAQ
Are late fees legally enforceable?
Yes, as long as the fee is disclosed in a signed contract and complies with your state’s law. A client is not required to pay a fee they never agreed to. Document your terms clearly and confirm the client accepted them before work starts.
Do all states allow the same late fee rate?
No. Late fee limits vary by state because most states regulate them through usury law, contract law, or industry-specific statutes rather than a single federal rule. A rate that is standard in one state can exceed the legal limit in another, which is why a collections attorney should confirm your rate before you put it in a contract.
Can I add late fees to accounts already sent to collections?
It depends on your state and your contract terms. A collections attorney can tell you whether fees that accrued after placement can be included in the claim. This is one more reason to get legal input from the start, not after an account is already overdue.
Should I waive late fees for long-term clients?
That is a judgment call. A client with a long history of on-time payments may warrant a one-time exception and a direct conversation. But waiving fees regularly teaches every client that the policy is flexible, which defeats its purpose.
What is the difference between a late fee and interest?
A late fee is a fixed charge applied once a payment is overdue. Interest is calculated as a percentage of the balance owed and can keep growing over time. Both can appear in a late payment policy, but they are treated differently under state law and may be subject to different limits.
When should I involve a collections agency?
When follow-up and late fees have not moved an account, and the balance is hurting your cash flow, it is time to bring in a professional collections partner. Acting earlier tends to produce better results than waiting until a balance is severely overdue, and a partner like Kinum can also walk you through what debt collectors can and cannot legally say during that process.
Recovering Revenue When Late Fees Are Not Enough
A solid late fee policy protects your cash flow, sets clear expectations, and cuts down on the time your team spends chasing payments. Getting it right starts with the basics: a compliant rate, a signed contract, and consistent enforcement.
When an account outgrows what your team can handle in-house, Kinum can help. Our Connect and Collect process gives your business a structured, people-first path to recovering past-due balances, with flat-fee and contingency-based options built to fit your size. Reach out to talk through your specific situation, or call 888-471-0280 directly.