
Medical debt settlement is a process where a third-party company talks to your creditor and asks them to accept less than the full amount you owe. It can lower your balance, but it comes with real costs: long-term credit damage and a tax bill many people never see coming.
Medical debt is one of the most common financial burdens facing American families. Research shows that roughly 66% of bankruptcies cite medical expenses as a factor. If you are dealing with an overdue medical bill, knowing your options matters. What settlement means for your credit, your taxes, and your relationship with your doctor’s office can affect you for years.
This article breaks down how medical debt settlement works, what it actually costs beyond the negotiated balance, and how it compares to working with a collections agency.
What Is Medical Debt Settlement?
Medical debt settlement is when a creditor agrees to accept a reduced payment as full satisfaction of a past-due debt. The amount is usually paid in a lump sum. A third-party settlement company handles the negotiation on your behalf.
Here is how the process works:
- You stop paying your medical account and start depositing money into a savings account that the settlement company controls.
- Once enough has built up, they contact your creditor and offer a lower payoff amount.
- If the creditor agrees, you pay that amount. The remaining balance is forgiven.
- The account is then marked on your credit report as “settled” or “paid for less than the full balance.”
Settlement companies charge a fee for this service. It may be a flat rate or a percentage of the debt enrolled. Those fees vary widely and should be part of your cost comparison.
What Are the Pros of Medical Debt Settlement?
For people in real financial hardship, settlement offers some relief:
- You pay less than the full balance. If the negotiation is successful, you resolve the debt for less than you originally owed.
- It wraps up in one payment. Settlement closes the account in a single transaction rather than months of installments.
- Collection activity stops. Once the settlement is paid, the collection process on that account ends.
But the benefits come with real costs. The downsides are worth understanding before you decide.
What Are the Cons of Medical Debt Settlement?
1. It Damages Your Credit Score
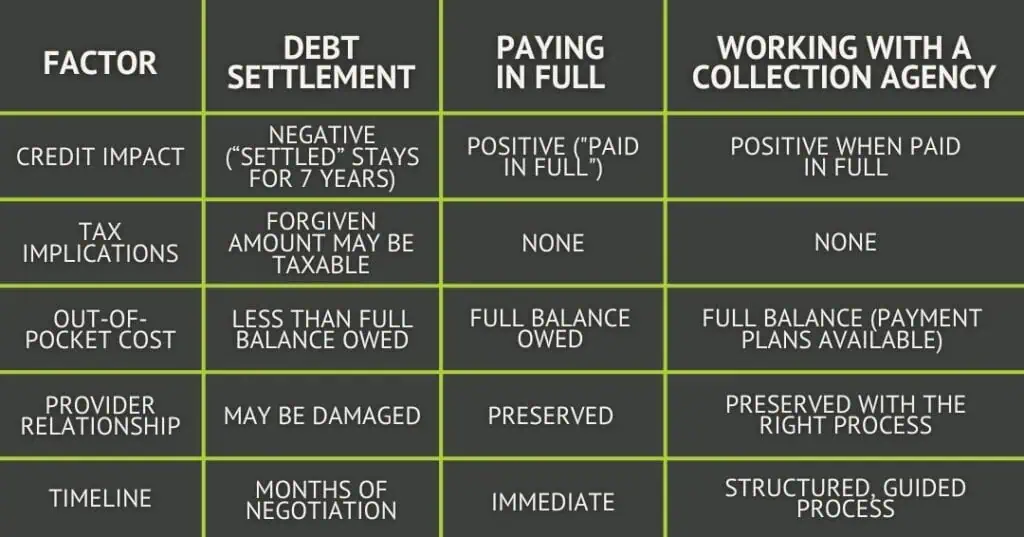
When an account is settled for less than the full balance, it shows up on your credit report as “settled.” That is a negative mark. It stays on your report for seven years from the date the account first went past due.
That is different from a “paid in full” notation. Lenders treat a settled account as a sign that you did not repay what you originally agreed to. That can affect your ability to get loans, credit cards, or housing for years afterward.
2. The Forgiven Amount May Be Taxable
This is the cost most people miss. When a creditor forgives part of what you owe, the IRS counts the forgiven amount as income. If you owed $5,000 and settled for $3,000, that $2,000 difference may be reported to you and to the IRS on Form 1099-C.
Per IRS Topic 431, forgiven debt is treated as ordinary income unless an exception applies. Insolvency and bankruptcy discharge are the most common exceptions. Talk to a tax professional before starting so you know what to expect at tax time.
3. The Process Is Not Guaranteed
Creditors do not have to say yes. While you save up in a settlement account and wait for talks to begin, your original balance may keep growing with interest and late fees. Collection contacts may continue too.
4. Settlement Company Fees Add Up
Most settlement companies take a cut of what you save. That fee reduces the actual benefit of a lower payoff amount.
5. It Can Strain Your Relationship with Your Provider
Medical debt is not like a credit card balance. Your provider may be someone you need to see again. Months of non-payment and a third-party negotiation can damage that relationship.
Is It Better to Pay Medical Debt in Full or Settle?
Paying in full is the better outcome for your credit. A “paid in full” account tells lenders you met your obligation. In some cases, it may even be removed from your report entirely.
A settled account tells a different story. It shows the debt was closed for less than owed. That notation stays for seven years and can affect lending decisions during that time.
If protecting your credit matters, paying in full, even through a payment plan, is the stronger choice.
Does Medical Debt Settlement Affect Your Taxes?
Yes, in most cases. When a creditor forgives $600 or more, the IRS requires them to file Form 1099-C and send you a copy. That forgiven amount is added to your taxable income for the year the settlement closed.
There are exceptions. If you were insolvent when the debt was forgiven, meaning your debts outweighed your assets, you may be able to exclude some or all of that amount using IRS Form 982. Debt cleared through bankruptcy is also generally excluded.
The bottom line: settlement does not just lower what you owe. It can swap one debt for a tax bill. That trade-off is worth understanding before you commit.
Medical Debt Settlement vs. Working with a Collection Agency
When a medical bill goes to a collection agency, the goal is different from settlement. A professional agency works to help you pay the full balance, not a reduced one.
At Kinum, that means setting up payment plans that fit your budget, keeping communication clear and respectful, and helping providers get paid without harming the patient relationship. The goal is always a paid-in-full result. No tax hit. A positive credit mark instead of a settled one.
If you can pay over time, working with a collection agency usually leads to a better outcome than settlement.
Frequently Asked Questions About Medical Debt Settlement
Does medical debt settlement hurt your credit?
Yes. When an account is settled for less than the full balance, it is reported as “settled” on your credit report. That is a negative mark that stays for seven years from the original delinquency date. It can affect your ability to get loans, housing, or favorable interest rates during that time.
Is it better to settle medical debt or pay it in full?
Paying in full is better for your credit and your long-term finances. A paid-in-full account carries no tax consequences and reflects positively on your credit history. Settling saves money upfront but leaves a negative credit mark for seven years and may create a tax liability on the forgiven portion.
Does settling medical debt affect your taxes?
In most cases, yes. The IRS treats forgiven debt as taxable income. If a creditor forgives $600 or more, they must send you a Form 1099-C, and you may owe income taxes on that amount. Exceptions apply if you were insolvent or your debt was discharged in bankruptcy. Talk to a tax professional for guidance specific to your situation.
How long does a settled medical debt stay on your credit report?
A settled account stays on your credit report for seven years from the date the account first went past due. After seven years, it is removed automatically.
What if I cannot pay my medical bill at all?
There are options before settlement. Many providers offer hardship programs, charity care, or interest-free payment plans. Working with a collection agency can also give you a structured path to pay the full balance over time, which protects your credit and avoids any tax consequences.
Know Your Options Before You Decide
Settlement can look like a simple fix. But the credit damage, possible tax bill, and company fees can make it more expensive than it seems.
Before going that route, ask whether a payment plan, hardship program, or collections process could get you to a paid-in-full result. That path protects your credit and avoids tax exposure.
If your account is already with a collection agency, you still have options. A professional agency will work with you to find a payment path that fits your budget and protects your financial future.
At Kinum, we start by connecting with you as a person, not just an account number. If you have questions about the collections process or how your account is being handled, call us at (888) 471-0280 or reach out through our website.