

If your organization works with a third-party collections agency, the Fair Debt Collection Practices Act (FDCPA) shapes how that agency can contact the people who owe you money. It is a federal law with clear limits on collection conduct, enforced by the Federal Trade Commission and the CFPB (Consumer Financial Protection Bureau), and understanding what it allows and what it bans protects your organization from legal risk while helping you choose the right partner.
Debt collection law is not limited to the FDCPA alone. State usury laws, state-specific consumer protection statutes, bankruptcy protections, and your collection agency’s own compliance practices all affect how your accounts receivable process should run. This article covers what to know at every level.
What Is the Fair Debt Collection Practices Act?
The FDCPA is a federal law passed in 1977 as part of the Consumer Credit Protection Act. The Consumer Financial Protection Bureau and the Federal Trade Commission enforce it today.
The law applies to third-party debt collectors, meaning agencies that collect debts on behalf of another party. It does not cover a business collecting its own debts directly, with a few exceptions. The FDCPA covers consumer debts, including medical bills, credit cards, student loans, and utility accounts. Business-to-business debts are not covered under the FDCPA, though other laws may still apply.
What Does the FDCPA Prohibit?
Failure to Verify the Debt
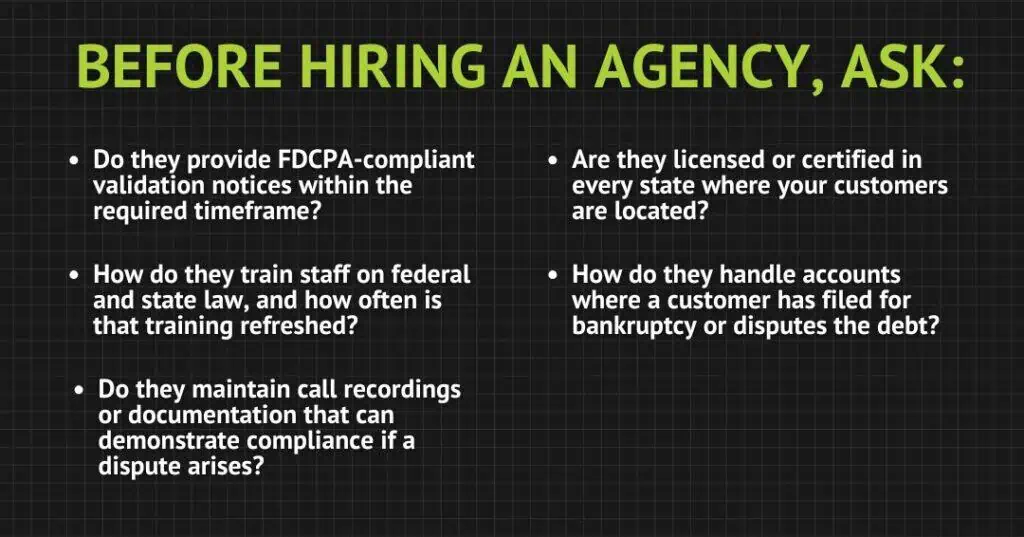
Collectors must be able to show proof that a consumer owes the debt. Under the law, a collector generally must send a written validation notice within five days of first contacting a consumer, stating the amount owed, the name of the creditor, and how to dispute the debt. If a consumer requests written proof within this validation period, the collector must provide it and pause collection until they do. Some states have strict timeframes within which to respond.
Harassment and Repeated Contact
Collectors may not harass, threaten, or use abusive language. In November of 2021, Regulation F was added to the FDCPA outlining rules that collection agencies must follow. For example, they may not call a consumer more than seven times in a rolling seven-day period without the consumer’s permission or make additional contact attempts for 7 days after speaking with the consumer. Collectors also may not contact a consumer’s family or friends except to locate a current address, phone number, or place of employment.
False Statements and Misrepresentation
Collectors cannot lie or mislead. They may not claim to be an attorney, a government official, a credit reporting agency, or a friend, and they cannot tell a consumer they owe a different amount than what is actually owed.
Impersonating a Government Agency or Threatening Arrest
Debt collection is a civil matter, not a criminal one. A collector claiming to represent a government agency, or threatening arrest over an unpaid debt, is violating the law outright.
Public Shaming
Collectors cannot publish or threaten to publish a list of consumers who allegedly refuse to pay debts, and they cannot contact an employer or coworkers to embarrass a consumer into paying.
Unfair Practices
Collectors cannot try to collect more than the amount owed, unless the original contract or state law allows it, and they may not deposit a post-dated payment before the date written on it.
Misleading Threats and Correspondence
Collectors may not threaten legal action they are not allowed to take or do not plan to take, and they may not send documents designed to look like court or government paperwork when they are not.
State and Federal Interest Rate Limits
Usury laws regulate the maximum amount a business can charge on overdue accounts and balances, and the specific limits vary from state to state. The federal Truth-in-Lending Act sets baseline requirements, but state usury laws can be stricter, so it is important to understand your specific state’s rules in addition to federal law. These laws include enough exceptions that it is worth confirming your practices with an attorney rather than assuming a blanket rule applies.
State Laws Can Add Additional Protections
The FDCPA sets a federal floor, not a ceiling. A number of states have their own debt collection statutes that go further than federal law, adding requirements around licensing, permitted contact hours, or language access. New York City, for example, requires collectors to provide a glossary of common debt collection terms in multiple languages. If your organization operates in or collects from consumers in several states, confirm that your process, or your collection partner’s process, accounts for the strictest applicable state law rather than only the federal minimum.
Bankruptcy Changes the Rules
If a customer or vendor has filed for bankruptcy, debt collectors and creditors must stop collection activity until the bankruptcy proceeding is settled. Continuing collection efforts after a bankruptcy filing is a legal risk regardless of how much is owed. An automatic stay takes effect the moment a bankruptcy petition is filed, and it applies even if your organization was not yet aware of the filing when contact was attempted.
Recent Rule Changes Worth Watching
Debt collection compliance is not static. Businesses in healthcare should also be aware of the No Surprises Act and its effect on patient billing, and any organization working with a collection partner should stay current on recent CFPB rule changes that continue to shape what compliant collection looks like. Charity care requirements are becoming increasingly prevalent across states, so it is best to make sure you are staying up to date with the latest regulations.
What to Look for in a Compliant Collection Partner
When you outsource collections, your collection agency’s compliance becomes your compliance in the eyes of your customers and, in some cases, regulators. A violation committed by your collection partner can still damage your organization’s reputation, even if you were not the one who made the call.
Documentation Protects Everyone
A compliant collection process is also a well-documented one. Keeping records of validation notices sent, contact attempts made, and any disputes raised protects your organization if a customer later claims they were not properly notified. This is one of the reasons working with an established agency that maintains its own compliance records, rather than handling collections informally in-house, reduces risk for growing businesses.
What This Means If You Are Being Contacted by a Collector
If your organization or someone connected to it has been contacted by a debt collector, it helps to know your rights. A collector cannot deceive you, threaten you, or misrepresent who they are. If you believe a collector has violated the FDCPA, your first course of action should be to call the company that contacted you and ask for a manager. The violation may be the result of a training issue that should be addressed. This also allows you to confirm that the collector who contacted you is the correct one before filing a formal complaint. If your issue is not satisfactorily resolved after your conversation with a manager, you can file a complaint with the Consumer Financial Protection Bureau, contact the Federal Trade Commission or your state attorney general, or pursue a lawsuit in state or federal court within one year of the violation.
Frequently Asked Questions
What is the Fair Debt Collection Practices Act?
The FDCPA is a federal law passed in 1977 that limits what third-party debt collectors can do when collecting consumer debts, including bans on harassment, false statements, and unfair collection practices.
Does the FDCPA apply to business-to-business debt?
No. The FDCPA covers consumer debts such as medical bills, credit cards, student loans, and utility accounts. Business-to-business debts fall under different laws.
Can a debt collector contact me after I file for bankruptcy?
No. Once a bankruptcy case is filed, debt collectors and creditors must stop collection activity until the bankruptcy proceeding is settled, assuming the debt was incurred before the bankruptcy.
Do state debt collection laws differ from federal law?
Yes. The FDCPA sets a federal minimum, but many states add stricter requirements around licensing, contact hours, or language access, so both levels of law apply.
Choose a Partner That Takes Compliance Seriously
At Kinum, Inc., our team stays current on federal and state debt collection law and trains regularly to make sure our practices reflect it. To work with a collection agency that puts compliance and transparency first, contact us today.