
Since November 30, 2021, updated FDCPA rules have governed how third-party debt collectors may use electronic communications, including text messages, email, and social media, to contact consumers. These rules, formalized under the CFPB’s Regulation F, modernize the Fair Debt Collection Practices Act for the digital age. They give consumers more control over how they are contacted while creating specific compliance obligations for collection agencies and accounts receivable teams.
If your team handles debt collection or manages a third-party AR strategy, understanding these rules is not optional. Violations expose your agency to consumer lawsuits, CFPB enforcement actions, and significant financial penalties.
Here is what compliant electronic communication in debt collection requires today.
Key Takeaways
- The updated FDCPA rules for electronic communication have been in effect since November 30, 2021. All third-party debt collectors must comply.
- There is no numeric cap on texts, emails, or social media messages, but all electronic communications must include a clear opt-out mechanism, and consumers can stop contact through any channel at any time.
- Phone calls are limited to 7 within any rolling 7-day period, per debt. After a live conversation, the collector must wait 7 days before calling again about that same debt.
- Opt-out and stop-contact requests can be made orally. Writing is not required, and collectors must honor the request regardless of how it is delivered.
- Before reporting a debt to a consumer reporting agency (CRA), collectors must first contact the consumer by phone, mail, or electronic message and allow reasonable time for response.
What the Updated FDCPA Rules Changed for Electronic Communication
The Fair Debt Collection Practices Act was originally passed in 1977, long before text messages, email, and social media existed. For decades, collectors operated in a gray area when it came to digital outreach. The CFPB’s Regulation F, which took effect November 30, 2021, closed that gap.
The updated rules explicitly permit third-party debt collectors to contact consumers by text message, email, and private social media message. They also set clear requirements around consent, opt-outs, timing, content, and how these channels interact with credit reporting obligations.
For collection agencies and businesses managing accounts receivable, these rules create both opportunity and responsibility. Electronic channels offer faster, more trackable communication. They also come with compliance requirements that must be built into every workflow.
FDCPA Rules for Text Messages and Email
Frequency
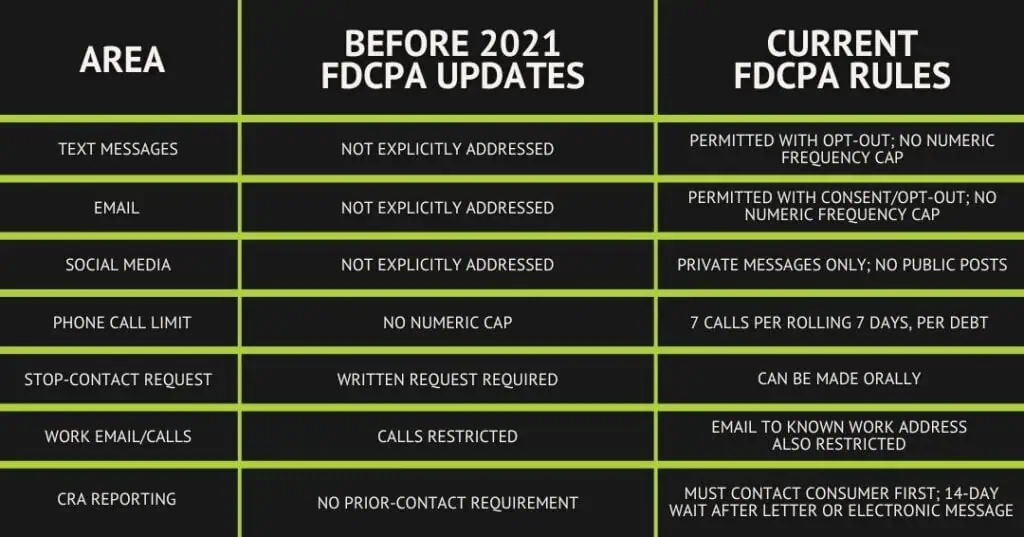
Unlike phone calls, the FDCPA does not set a numeric cap on how many text messages or emails a collector may send. However, that does not mean electronic outreach is unlimited in practice. The FDCPA’s broader prohibitions against harassment and excessive contact still apply to all communication channels, including texts and emails.
Opt-Out Requirements
Every text message and email sent in connection with debt collection must include a clear, functional opt-out mechanism. Once a consumer opts out of a specific channel, the collector must stop using that channel immediately.
Consumers can also request that a collector stop all contact through a specific method at any time. That request can be made orally. A verbal stop-contact request carries the same legal weight as a written one.
Timing Restrictions
Collectors may only send texts and emails at reasonable times. Contact is presumed inconvenient before 8 AM or after 9 PM in the consumer’s local time zone.
Work Email Restrictions
Collectors generally cannot send messages to an email address they know is a work address. Exceptions apply if the consumer previously used that work email to communicate with the collector about the debt and has not since opted out, or if the consumer gave direct consent for its use.
FDCPA Rules for Social Media in Debt Collection
Collectors may contact consumers through social media via private message only. Posting anything publicly on a consumer’s profile, timeline, or account is prohibited. This includes comments, wall posts, or any message visible to the consumer’s contacts or the general public.
Every private social media message must include the required opt-out mechanism, just like texts and emails.
Collectors also cannot send a friend or connection request in a way that reveals they are a debt collector, as this would effectively disclose the debt to anyone who sees the pending request.
FDCPA Phone Call Rules: The 7-7-7 Limit
The updated FDCPA rules introduced what is commonly called the 7-7-7 rule for telephone calls:
- A collector may place no more than 7 calls within any 7 consecutive rolling days about a particular debt
- After a live phone conversation about a debt, the collector must wait 7 days before calling again about that same debt
The 7-call limit applies per debt, not per consumer. If a consumer has multiple debts in collection, the limit applies separately to each one. The rolling period does not reset at the start of a calendar week.
Missed calls, attempted calls, and voicemails all count toward the 7-call limit.
FDCPA Electronic Communication vs. In-House Rules: A Quick Comparison
FDCPA Rules for Reporting to Consumer Reporting Agencies
One of the most significant changes in the updated FDCPA rules affects how and when debt collectors may furnish information to consumer reporting agencies (CRAs).
Before reporting a debt to a CRA, a collector must first:
- Speak with the consumer about the debt in person or by telephone, or
- Send a letter or electronic message about the debt and wait a reasonable period of time (14 calendar days) for any notice of undeliverability before furnishing
This requirement eliminates what was known as “passive collection,” where debt collectors would report debts to credit bureaus without ever notifying the consumer. Under current FDCPA rules, consumers must receive prior notice through at least one of these channels before a collector can furnish information to a CRA.
This makes compliant electronic communication even more operationally important. Text messages and emails now serve a dual compliance function: fulfilling contact obligations and satisfying the CRA pre-reporting requirement in a documented, trackable way.
Frequently Asked Questions About FDCPA Electronic Communication Rules
Can debt collectors legally text consumers?
Yes. The updated FDCPA rules explicitly permit debt collectors to send text messages to consumers. Every text must include a clear opt-out option, and collectors cannot send texts before 8 AM or after 9 PM in the consumer’s local time zone. There is no cap on the number of texts a collector may send, but the FDCPA’s general prohibition on harassment and excessive contact still applies.
Can a debt collector email me about a debt?
Yes. Email is a permitted communication channel under the FDCPA. Collectors must include an opt-out mechanism in every message and must avoid sending emails to a work address they know is employer-monitored, unless the consumer gave prior consent. Contact before 8 AM or after 9 PM is presumed inconvenient and should be avoided.
Can debt collectors contact consumers through social media?
Yes, but only through private messages. Collectors cannot post publicly on a consumer’s profile or page, comment on their posts, or send connection requests in a way that discloses the debt. Private messages must include an opt-out option.
How many times can a debt collector call?
Under the FDCPA’s 7-7-7 rule, a collector may place no more than 7 calls within any 7 consecutive rolling days about a specific debt. After a live phone conversation, the collector must wait at least 7 days before calling again about that debt. This limit applies per debt, not per consumer.
Does a consumer have to put a stop-contact request in writing?
No. Under the current FDCPA rules, a stop-contact request can be made orally. A verbal request to stop calls, texts, emails, or all contact carries the same legal weight as a written one. Collectors must honor it regardless of how it is delivered.
What must a debt collector do before reporting a debt to a credit bureau?
Before furnishing information about a debt to a consumer reporting agency, the collector must first contact the consumer by phone, letter, or electronic message. If contact is made by letter or electronic message, the collector must wait 14 days for any undeliverability notice before reporting to the CRA.
Compliant Electronic Messaging in Your AR Strategy
The updated FDCPA rules for electronic communication have been in effect since November 30, 2021. Collection agencies and businesses managing accounts receivable that have not built compliant electronic messaging into their workflows are carrying significant compliance exposure.
At Kinum, Inc., compliance is built into every step of our process. Our Kinum Complete System integrates the communication, opt-out, and CRA pre-reporting requirements of the current FDCPA rules so your accounts receivable strategy stays efficient and fully protected. Contact us today to learn more.